


Money20/20 2026: Building the Next Generation of Fraud Verification
Get Unlimited Access to IPinfo Lite
Start using accurate IP data for cybersecurity, compliance, and personalization—no limits, no cost.
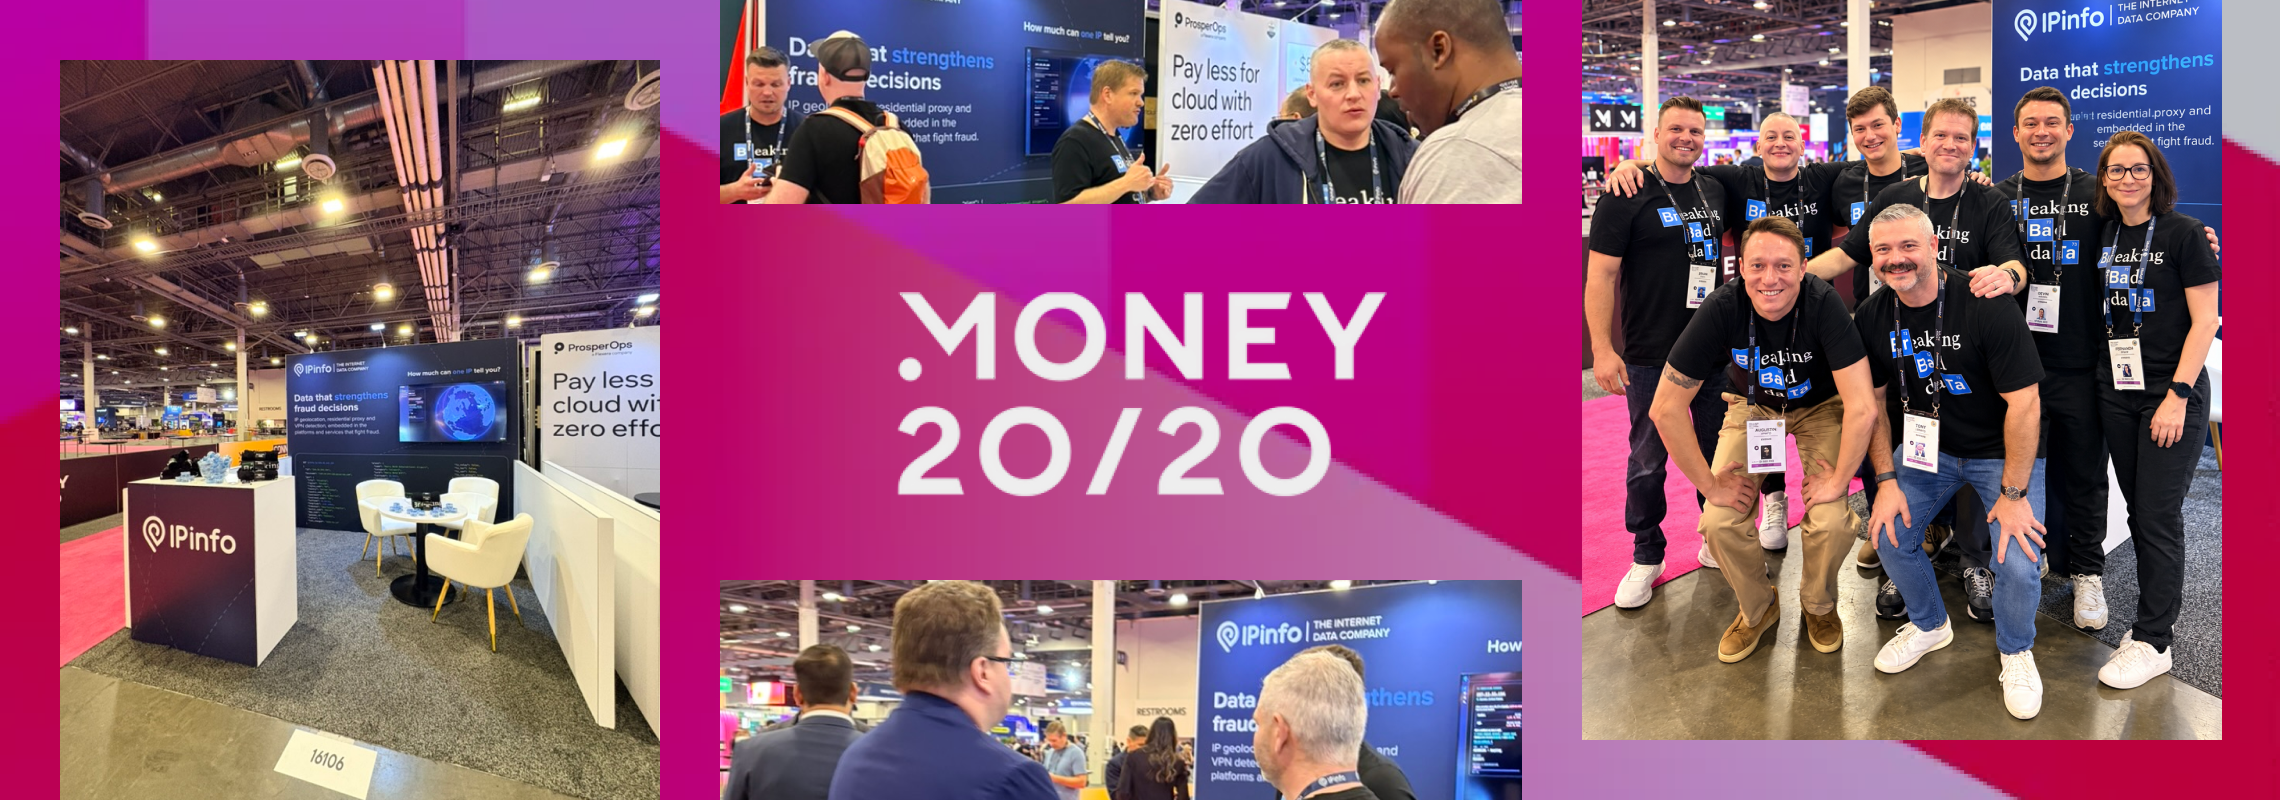
Sign up for freeAfter attending Money20/20, I can safely say that there's no shortage of people convinced they can build a better financial services business.
Founders with ambitious ideas, investors looking for the next big thing, and established vendors who have already learned a few expensive lessons were all collected under one roof in Las Vegas.
What interested me was how many of our conversations came back to traffic. Whether we were talking about fraud, compliance, or AI agents, the underlying challenge was remarkably similar: how do you know who, or what, you're dealing with?
Before the event, I'd written about how increasingly sophisticated fraud is becoming harder to distinguish from legitimate customer activity. Three days at Money20/20 reinforced that concern, but also gave me a lot of optimism about the people building the tools to address it.
Building the Next Generation of Fintech
One of the things I appreciate about Money20/20 is how deliberately it brings together the different parts of the financial services ecosystem.
The Startup Hub is a good example. It's designed to connect founders with investors, customers, and potential partners. That includes Airwallex, whose early participation helped secure its Series A funding, and Parcha AI, which has used the event to develop relationships with investors and customers.
There's a tendency to think innovation comes from startups and scale comes from established companies. In practice, financial services needs both, and increasingly needs them working together.
A startup might develop a clever new approach to identity verification, but it still needs reliable data, integration into existing systems, and a way to convince a regulated institution to use it. None of those things is particularly glamorous. All of them matter.
The opportunity for product managers is enormous. They're building tools to address threats that financial institutions already struggle with, while preparing for new forms of impersonation and automation. And they're doing it in an industry where getting things wrong can have serious consequences for both the business and its customers.
Making Verification Smarter
Fraud was easily the most common topic at our booth, and often raised by people outside dedicated fraud teams. Product executives, engineers, and founders were all looking for ways to identify suspicious activity before it becomes an expensive problem.
One bank wanted to filter suspicious traffic before initiating a Know Your Customer (KYC) check. Every verification step has a cost, financially and in terms of customer experience. If you're making every customer go through the most expensive process, you're probably solving the wrong problem.
The interesting opportunity for product teams is to determine where additional verification is actually needed. Understanding whether a connection originates from a hosting provider, VPN, or residential proxy can help make that distinction earlier. None of those signals proves fraud on its own, but together with other evidence, they can help teams decide when to investigate further.
Compliance introduces another dimension.
One thing I've noticed in conversations with financial services companies recently is a growing appetite for evidence. Not another score that tells you something is suspicious. Actual evidence that explains why.
Several compliance professionals at Money20/20 wanted information they could put into a report. Geographic restrictions were a recurring concern, particularly among crypto exchanges and payment providers. One founder was focused on sanctioned jurisdictions.
If you're restricting access to a financial service based on someone's location, you'd better be able to explain how you reached that conclusion.
For the companies building fraud and compliance products, the challenge is to make verification both more efficient and more defensible. Financial institutions have spent years removing friction from the customer experience. Nobody wants to undo that progress, least of all their customers.
The Next Challenge Is Know Your Agent
Perhaps the most interesting development of the week was a question several companies raised independently: can we identify AI agents interacting with their services? They called it Know Your Agent, or KYA. (Just what financial services needed, another acronym!)
We've spent years building systems to verify that a customer is who they claim to be. Now we need to work out what happens when the customer isn't actually the one interacting with us.
For example, someone authorizing an AI agent to find a better credit card, manage subscriptions, or make a payment. The financial institution receiving that request needs to establish whether the agent is legitimate, whether it has permission to act, and whether the transaction itself is appropriate.
At Money20/20, we heard two versions of this problem.
One was about infrastructure. Is the agent connecting through a hosting network, VPN, or residential proxy? These are familiar questions, and our existing data can help answer them.
The other was about attribution. If a request claims to come from ChatGPT or Claude, how do you verify that?
A user-agent string is easy to impersonate. Verifying the origin of automated traffic requires stronger evidence, particularly when agents operate on shared infrastructure. Our team has already started investigating how we can provide more useful data around this.
But verifying an agent's network origin is only part of the challenge. Knowing where a request comes from doesn't establish who authorized it or what it's allowed to do.
Those are different problems, and solving them will require collaboration across the identity verification ecosystem.
For product managers, this is a fascinating opportunity. The tools being built today will need to accommodate financial interactions initiated by people, software, and agents acting on someone else's behalf. It's an emerging category with plenty of unanswered questions, and I expect we'll see a lot of innovation here over the next few years.
Plenty Left to Build
What I took away from Money20/20 was how many companies are working on different aspects of these issues, and how much opportunity there is to bring those capabilities together.
The next generation of financial services will need to verify people, machines, and increasingly the agents acting between them. That will require new products, better evidence, and collaboration between companies that might otherwise consider themselves competitors.
Our role at IPinfo is to provide the network intelligence that helps those companies build better verification tools. We don't make the fraud decision for them. We give them evidence they can use to make their own.
There were plenty of people in Las Vegas with ideas about what the next generation of financial services should look like. I'm looking forward to seeing what they build.
Share this article


About the author
As Co-CEO of IPinfo, Paul has spent two decades at the intersection of internet infrastructure and enterprise technology. He's previously held executive positions at Puppet, Dyn & Oracle, helping build and democratize access to the modern internet.